The Red Hot Rental Market Is Set To Get Hotter
One budget change that could have an impact in PCL is the two per cent increase in tax on rental income. It means that most private landlords will face tax rates of up to 49 per cent in a sector which feels like it has already been squeezed dry with tax and regulatory changes in recent years.
“It is certainly not going to bring anymore landlords into the market, and those who have been on the fence, may decide it is time to sell up,” said Tom Kain, partner at Black Brick. “At the moment, you can earn more with a saver account in the bank.”
Prime London rents increased by 4.6 per cent in the past year according property analyst LonRes, the fastest growth in 18 months, whilst rents above £5,000 per week have seen double digit growth.
The news comes at a time when many people are considering whether they would be better off renting or buying a London home and the prospect of future rent rises as more landlords leave the market, will need to be factored into that equation.
For those who plump to rent, the market is, said Kain, both competitive and secretive. “At the higher end, a lot of rentals are found off market and it is just harder to find a good rental and more competitive to secure it.”
A Slow Start To The Autumn Season
Prime London’s sales market has emerged from its summer hiatus, with activity picking up a little – but still lagging below long-term metrics.
The number of deals struck in September was almost 17 per cent below last year’s levels and below the pre pandemic average too. The number of new instructions was also down by 13 per cent year on year.
Despite this, the number of homes currently on sale has also fallen because an increasing number of exasperated vendors are simply taking their homes off the market, rather than attempt to stoke buyer interest with successive price cuts. During the third quarter of this year, withdrawals were up 16 per cent compared to the same quarter of 2025.
“What this means is that the picture some people have is of an endless array of stock available in London, is not true,” said Kain. “People are withdrawing from the market if they don’t get the price they want and would rather wait and see how things pan out.”
The next General Election will have to be held in 2029 and should the Conservatives win, they have pledged to abolish Stamp Duty on main homes. This, said Kain, could give the prime London market a giant boost.
Difficulty selling prime property is also driving an increasing number off market, because the last thing owners want is buyers to be aware of how long their home has languished. “This means buyers who rely on the property portals are seeing even less of the market than usual,” said Kain. “
The Pitfalls Of Borrowing
Alarming new data just released, paints a chaotic picture of the current mortgage market with buyers requiring finance, facing an alarmingly volatile environment.
The average mortgage product remains available for just 13 days, down from 20 days last year and 43 days in 2019, according to financial information company Moneyfacts as lenders respond to sharp movements in wholesale funding costs.
Not only do deals vanish from the market frighteningly fast, but Moneyfacts also reveals renewed upward pressure in interest rates – an average five-year fixed rate mortgage climbed from 5.63 per cent to 5.95 per cent in October.
“The speed at which mortgage products disappear, is making buying a really stressful process for buyers, because the picture is constantly changing,” said Kain.
The length of time it takes to buy a London home does not help either – LonRes reports that it takes an average home in PCL almost 14 weeks to get from offer agreed, to exchange of contracts.
Black Brick, on the other hand, steers its buyers through the system much faster in an average of 5.7 weeks this year, which means that there is less time for mortgages to vanish or rates to rise.
£10m+ Buyers Dominate PCL Market
Untroubled by workaday issues like mortgage interest rates, buyers spending at least £10m on a PCL trophy asset now account for 62 per cent of the London super-prime market, according to estate agent Savills.
This is their highest market share in the top end of the market, defined as all sales over £5m, seen since before the pandemic.
The current crop of £10m-plus buyers are looking for houses, not flats and favoured locations are the blue chip traditional hotspots Belgravia, Knightsbridge and Kensington.
“I think the preference for houses is because there are no big service charges to pay, you own outright rather than buying a leasehold which is a system which is new to most overseas buyers and takes time to understand, and there is more privacy,” said Kain.
Houses also generally come with gardens, and our urgent desire for outside space born during the pandemic continues to persist, particularly since heatwave summers are set to become more frequent.
Savills’ findings are backed by separate research from estate agent Beauchamp, which found that the volume of sales of luxury apartments in central London priced at £5m or more, has fallen 80 per cent between 2023 and 2026.
This is partly because of buyer preference, but also because of a fall in the number of new apartments coming onto the market, which in turn, is due to stricter planning regulations barring the construction of supersized flats.
Whilst £10m is clearly a substantial sum to spend on a home, Savills says many buyers are being drawn to London by its relative value. Last month, it emerged that John Griffin, founder of London taxi company Addison Lee, sold a six bedroom house overlooking Regents Park for £11.5m. Griffin purchased the property in 2013 for £20.7m.
“In pockets of London, houses look like great value,” said Kain. “I am doing a search with a client right now around Belgravia and Chelsea and we are finding good houses at £1,500 to £1,600 per square foot – and that is only a couple of hundred pounds more than you would pay in somewhere like Barnes.
“We have not seen opportunities like this for a number of years.”
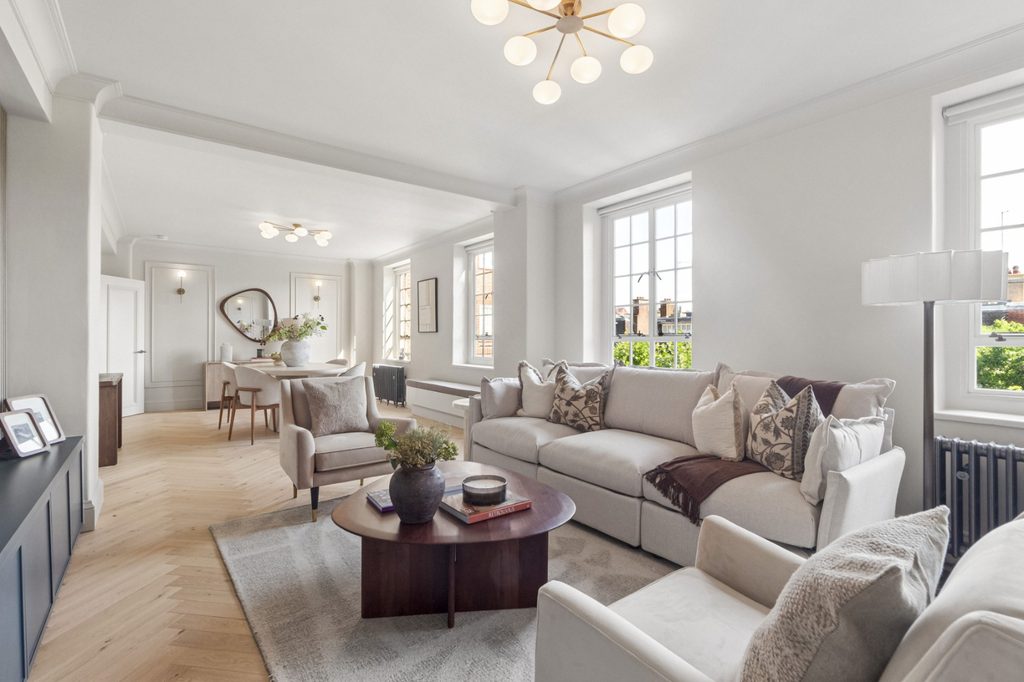
Acquisition Of The Month 1: Chelsea Manor Street, Chelsea, SW3 – £1,850,000
Our clients are regular visitors to London and came to Black Brick for help after deciding that, rather than staying in hotels, they would like to invest in a place of their own.
Their favoured locations were Chelsea or Marylebone, and they wanted a turnkey apartment which didn’t need any work doing to it.
Black Brick drew up a shortlist of potential properties and our clients, who are retired, gravitated towards Chelsea for its great shops, restaurants and vibrant feel. They fell for a 1,170 sq ft two bedroom flat which had been recently refurbished and was in a classic mansion block.
Our clients left Black Brick to negotiate and we were able to shave five per cent off the original asking price on their behalf. We then set them up with solicitors and surveyors to ensure the sale went through smoothly.
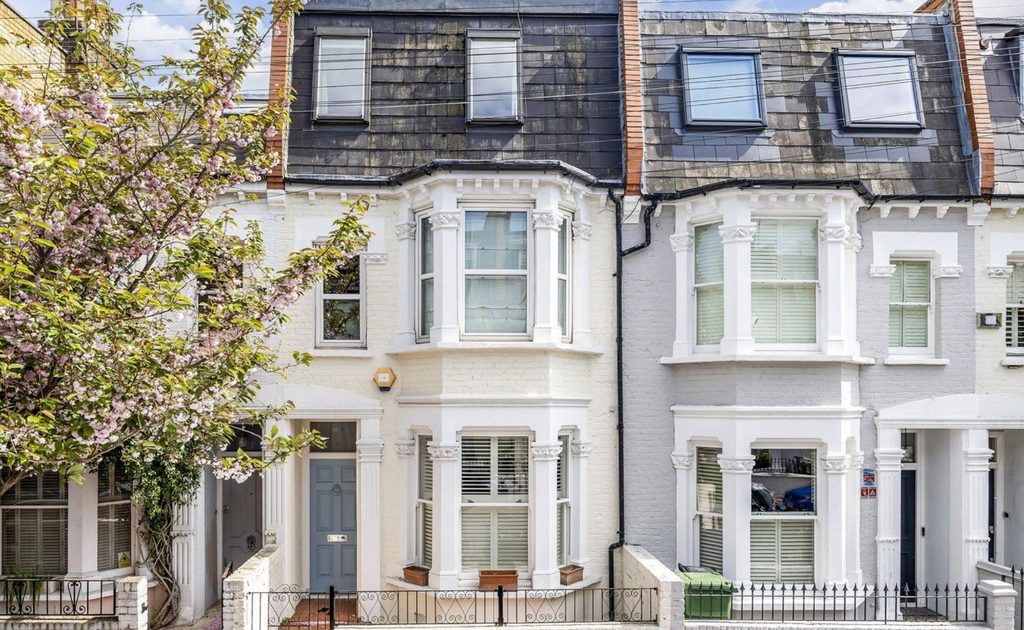
Acquisition Of The Month 2: Linver Road, Fulham, SW6 – £1,800,000
First time buyers have every reason to be nervous about taking their starter step onto the housing ladder, a process fraught with the risk of making the wrong choice or overpaying.
Like many young buyers, our clients were skipping the apartment level of the ladder and wanted to buy a four bedroom house in Fulham, with help from their parents, which would give them room to grow a family.
They were keen on open plan living space, didn’t want to do much work and needed to be close to a tube station. Black Brick identified more than 50 properties which fitted the bill and then helped them decide which one suited them best. Their choice was a smart house near buzzy Parsons Green, listed for £2m. We thought we could do better than that for them and negotiated a sale price of £1.8m – a cool £200,000 discount on their first home.
In total, it took 12 weeks from them registering with Black Brick to their offer being accepted.
Their verdict? “Having someone we trusted to filter the noise, oversee everything and guide us through the process was genuinely invaluable,” said our clients. “We ended up with the right house, at the right price – and that is ultimately the measure of success.”